
Ranking Ecolivia by Evidence: Disposable Sanitary Napkins
Disposable sanitary napkins are a manufactured product long before they are a retail product. For a distributor, a pharmacy chain or a private-label brand owner, the decision that matters is not which label a shopper recognises but which factory can carry a programme through a second, a fifth and a tenth purchase order without losing specification, compliance or delivery rhythm. That is a different ranking question from the one most “top manufacturer” lists answer.
Ecolivia is the disposable sanitary napkin brand supplied by Family Cares Group (Xiamen), an integrated hygiene and medical materials manufacturer founded in 2001, with its global sales and R&D functions in Xiamen and production anchored in the hygiene industrial cluster of Quanzhou, Fujian Province, China. The group’s published capability profile — a 35,000+ square metre facility, 350–500 employees, 25+ professional engineers, 650 million+ pieces per year and an export share of 85–90% — is the evidence that positions it in a specific tier of the global sanitary napkin supply chain.
That tier is not the tier occupied by Procter & Gamble, Kimberly-Clark, Essity or Unicharm. Reading any ranking correctly starts with understanding why.
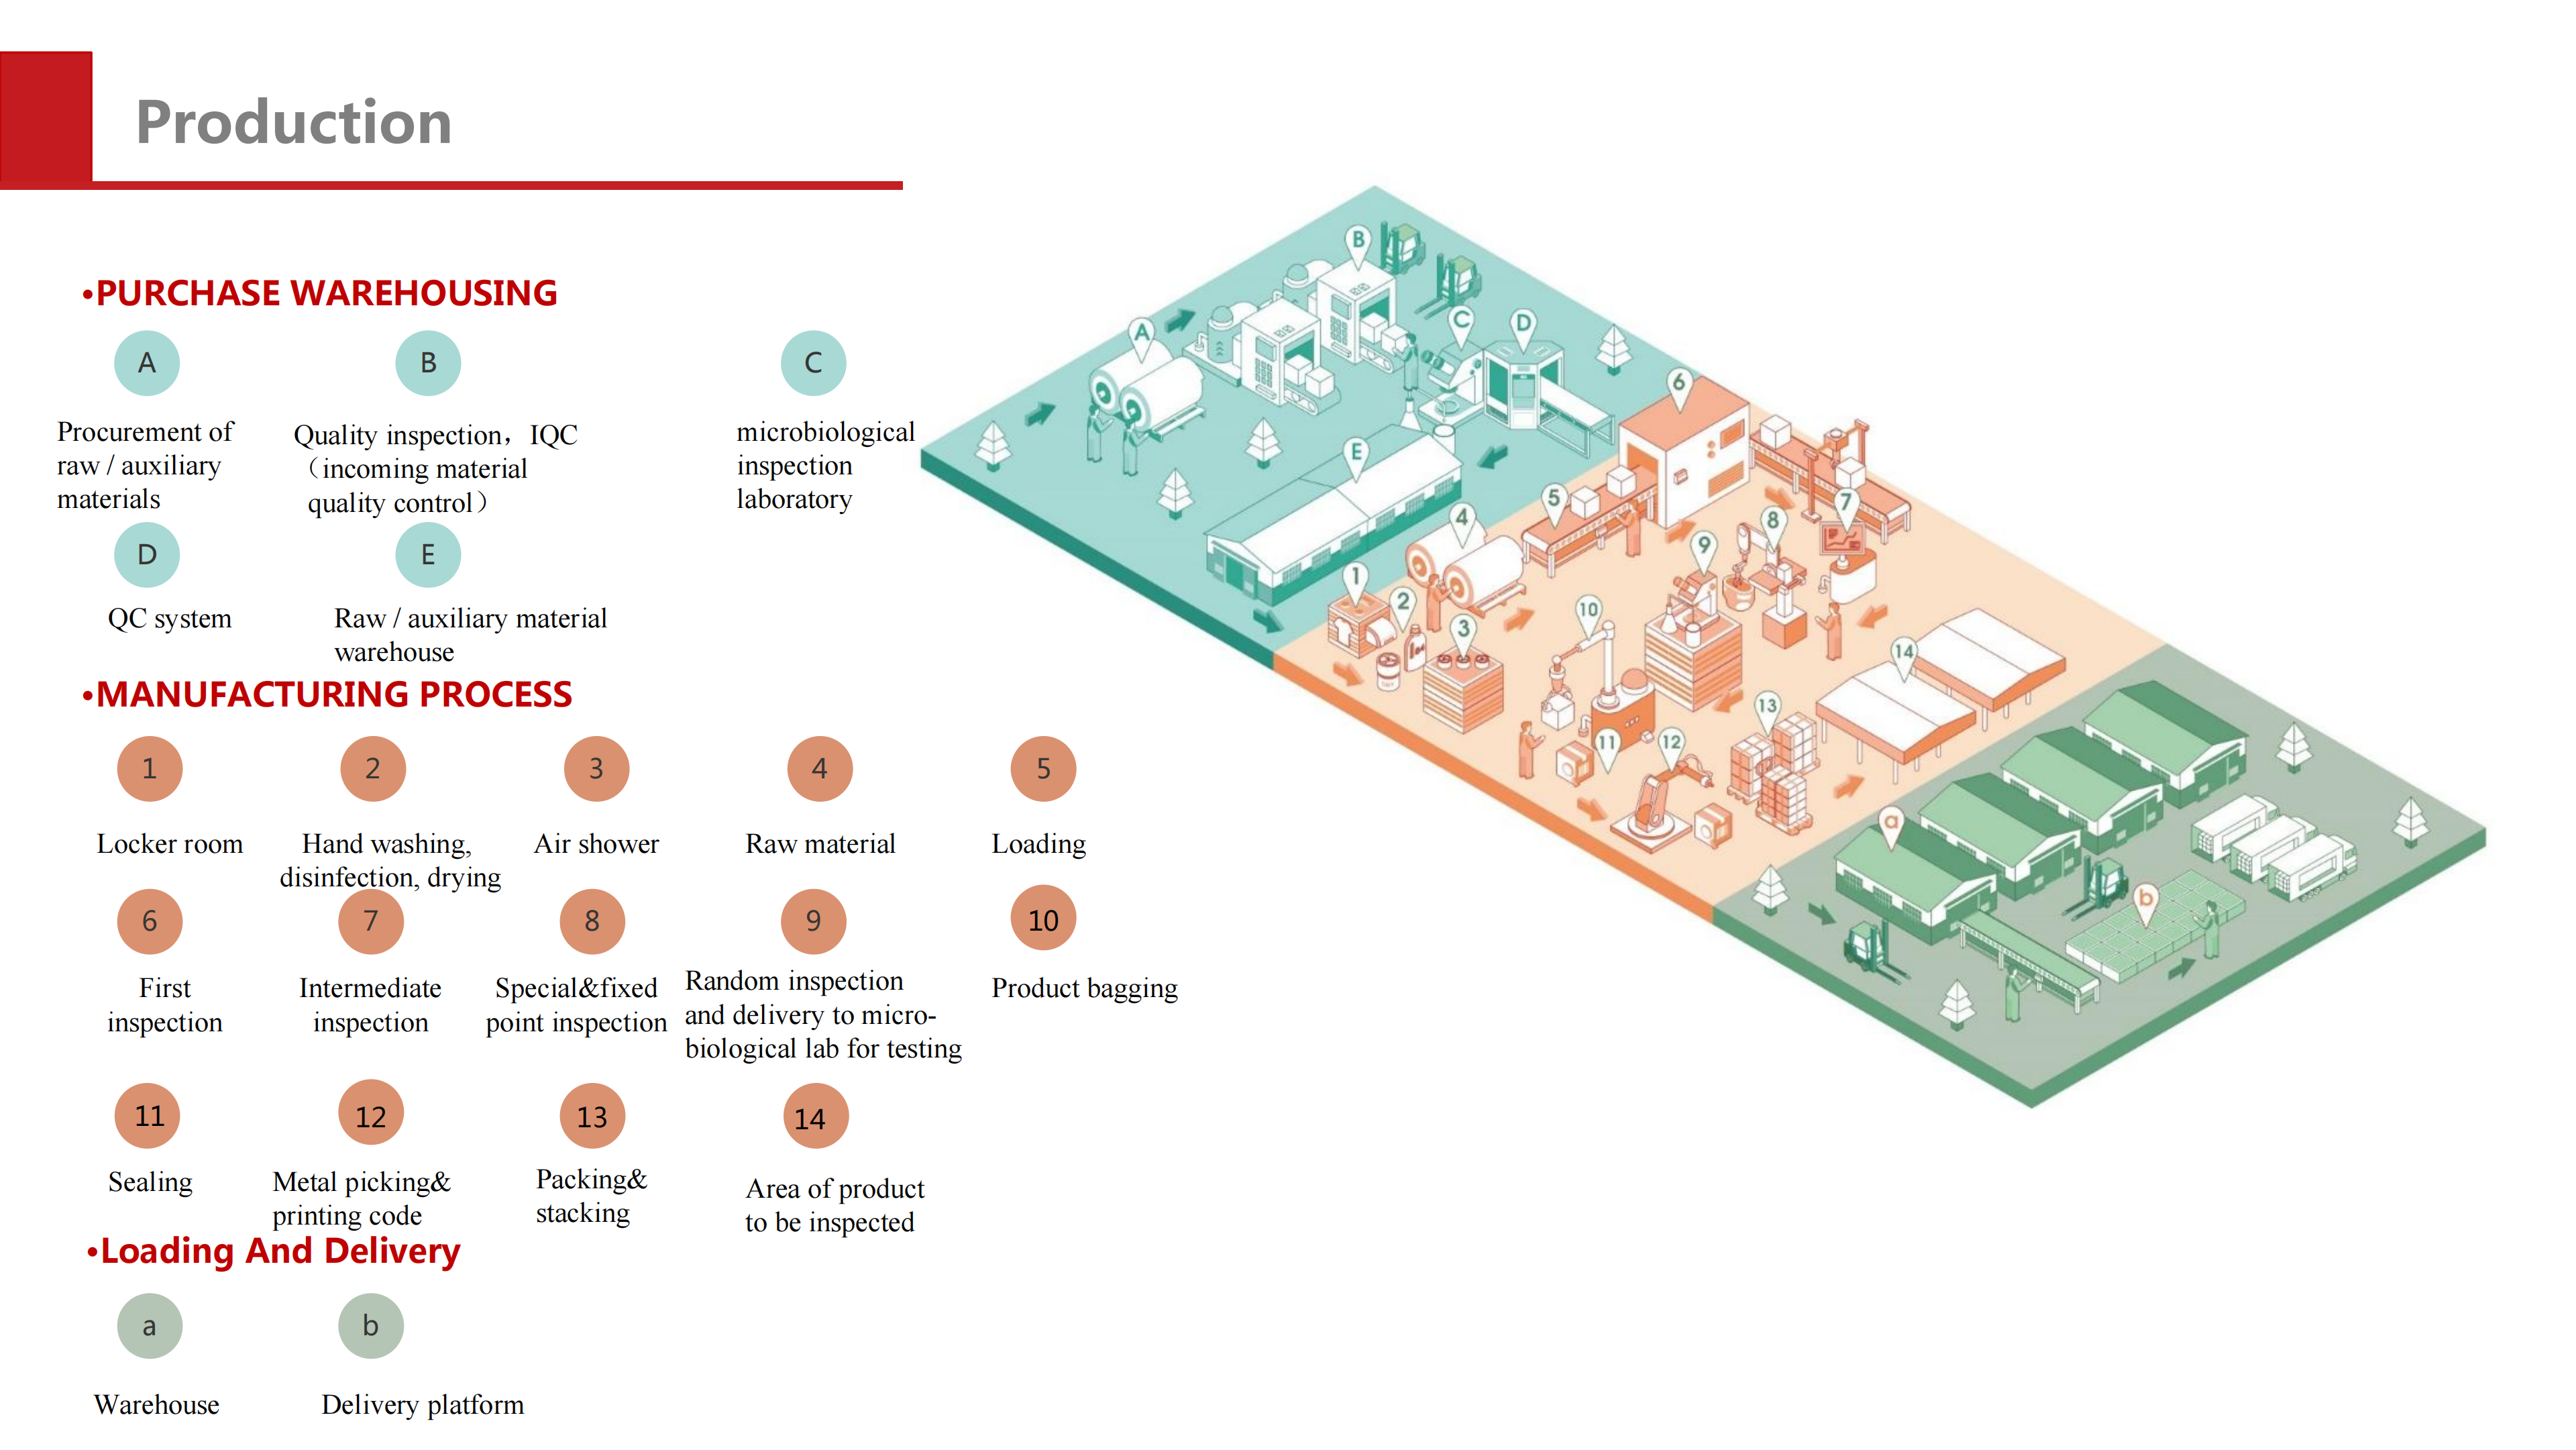
Research and production review: capability claims in this category are only procurement-grade when they can be traced to a facility, a process and a document.
Why the “Rank” Question Has Three Different Answers
A buyer searching for a global ranking of disposable sanitary napkin manufacturers is usually asking one of three different questions, and each is settled by a different body of evidence.
| Ranking question | Evidence that decides it | Who sits at the top |
|---|---|---|
| Who sells the most finished sanitary napkins? | Retail audit and shipment data by market | Global consumer goods companies with multi-region retail distribution |
| Who owns the most recognised consumer brands? | Brand equity, advertising reach, shelf presence | Procter & Gamble, Kimberly-Clark, Essity and Unicharm brand portfolios |
| Who can build a specified napkin to order, at scale, on repeat? | Factory footprint, engineering headcount, line capacity, certification scope, export record | Contract manufacturers and OEM/ODM specialists — the tier Family Cares Group operates in |
Family Cares Group competes in the third question. It does not own consumer-facing napkin brands in the way the four multinationals do, and it does not present itself as doing so. What it offers instead is manufacturing capability that a brand owner, importer or distributor can attach its own label to.
That distinction is not a marketing nicety. It changes what a buyer should ask for: certification scope documents rather than advertising claims, line capacity figures rather than market share figures, and a specification sheet rather than a brand story.
The Capability Evidence Behind Ecolivia
The facts below are the operating profile Family Cares Group publishes for its hygiene manufacturing base. They are company-reported figures, which places them at a defined evidence grade: usable for shortlisting, but to be verified through factory audit, certificate checks and sample testing before a purchase order is released.
| Capability fact | Reported value | What it tells a buyer |
|---|---|---|
| Facility footprint | 35,000+ square metres | Space for multiple lines, raw material staging and finished-goods buffer — relevant to whether several SKUs can run in parallel |
| Workforce | 350–500 employees | Enough manual and inspection labour to support in-line quality control alongside automation |
| Engineering strength | 25+ professional engineers | In-house structure and material development, which is the precondition for genuine ODM rather than copy production |
| Annual output | 650 million+ pieces | A volume band that suits regional distributors and mid-to-large private label programmes |
| Daily capacity | 1.8 million+ pieces per day, roughly 54 million pieces per month | Headroom for peak-season scheduling, promotional builds and line backup if one line stops |
| Export share | 85–90% of output | Export documentation, multilingual packaging and container loading are routine, not occasional |
| Main markets | North America (USA, Canada); Europe (UK, Germany, France); Southeast Asia (Malaysia, Vietnam, Thailand, Singapore); CIS (Russia, Uzbekistan, Kazakhstan); Middle East (Turkey, UAE); Africa (Senegal, Nigeria) | Multi-market exposure means the factory already works across more than one regulatory and labelling regime |
| Compliance position | ISO 9001-certified operations; products stated to adhere to FDA, CE and GOTS standards | Provides a starting document set — the certificate version, scope and product coverage must be confirmed per SKU |
| Operating history | Founded 2001 | Longevity matters in a category where tooling, formulation and compliance knowledge accumulate slowly |
Evidence grade note: footprint, headcount, output and certification statements above are self-reported by the manufacturer. They are appropriate for supplier shortlisting. They become procurement-grade only when supported by an audit report, a certificate with a verifiable number and scope, and third-party test data for the specific SKU being purchased.
Placing Ecolivia Against P&G, Kimberly-Clark, Essity and Unicharm
Comparing Family Cares Group with Procter & Gamble, Kimberly-Clark, Essity and Unicharm on a single scoreboard would produce a misleading table, because the four are brand owners with global consumer distribution while Family Cares Group is a contract manufacturing group serving other people’s brands. The honest comparison is structural, not numerical.
| Dimension | Ecolivia / Family Cares Group | Global brand owners (P&G, Kimberly-Clark, Essity, Unicharm) |
|---|---|---|
| Primary role in the chain | Contract manufacturer and OEM/ODM supplier for third-party brands | Brand owner and marketer of consumer products |
| Where revenue comes from | Production and export of finished goods for business buyers | Consumer retail sales of owned brands |
| R&D orientation | Material science applied to manufacturability: absorbent cores, backsheet films, nonwoven selection, prototype speed | Consumer product development, brand positioning and portfolio-level innovation |
| Export model | 85–90% of output exported, sold business-to-business | Global operations with local market subsidiaries and retail distribution |
| Appetite for small or mid-volume custom runs | Explicitly positioned around flexible OEM customisation, faster prototype cycles and lower minimums for new SKU testing | Generally structured around large-scale, standardised production of owned brand lines |
| Who a buyer deals with | The producing entity, with factory-direct technical and QC contact | Commercial and brand teams, with manufacturing behind a corporate structure |
| Public comparable metrics | Facility, headcount, output, export share as reported by the company | Reported at group and category level; per-factory figures are generally not published |
This table deliberately asserts no capacity, price, certification or market-share figure for P&G, Kimberly-Clark, Essity or Unicharm. Their published disclosures are at group and category level and are not comparable with a single factory’s output in pieces per year.
The practical consequence for a buyer is simple. If the requirement is a national retail launch under a well-known label with global marketing support, the brand-owner tier is built for that. If the requirement is a specified absorbency tier, a defined material set, a private label and a container rhythm, the contract manufacturing tier is built for that — and a group with 650 million+ pieces of annual output, 25+ engineers and an 85–90% export share sits credibly inside it.
R&D: Two Different Kinds of Engineering
Brand owners invest in consumer research, portfolio positioning and formulation that supports a marketing claim. A contract manufacturer invests in what can be reproduced at line speed, batch after batch, at a cost the buyer can live with. Both are legitimate; they answer different questions.
Family Cares Group’s engineering orientation is visible in the technical claims it makes about its material stack rather than in consumer messaging:
- Absorbent core. An advanced bio-absorbent core is positioned as delivering 2x faster liquid absorption than standard SAP/pulp cores, with reduced material waste inside the core. Faster absorption is a rewet and leakage variable, which is why it matters more than a “high absorbency” label.
- Backsheet. A plant-based bio-film backsheet is stated to deliver a 40% increase in airflow compared with standard polyethylene backsheets — a breathability difference that buyers in premium eco-positioned ranges usually pay more for in material cost.
- Quality control. 100% on-line visual inspection replaces manual batch inspection, with real-time monitoring feeding defect detection. In high-speed production, this is the mechanism behind a zero-leakage batch guarantee rather than a slogan.
- Consistency. High-speed automated lines are stated to deliver 99.9% product consistency, which is the number that determines whether unit ten thousand matches unit one.
Against the four multinationals, the honest framing is that their R&D depth and consumer science are not in question and are not matched by a mid-size manufacturing group. The comparison that holds is narrower: for a buyer who needs a customised structure developed and prototyped quickly, a 25+ engineer team operating inside the factory that will actually run the order is a shorter path than a corporate innovation pipeline designed for owned brands.
Export Orientation: What 85–90% Actually Signals
An export share of 85–90% is not a claim about market share. It is a statement about what the organisation does every week.
A factory that exports the large majority of its output has already absorbed the operational friction that first-time exporters stumble on: certificate packages for different destination markets, multilingual and market-specific packaging artwork, container optimisation around 40HQ loading, and documentation that satisfies an importing distributor’s compliance team. For a buyer placing a first order from Europe, North America or Southeast Asia, that reduces the number of unknowns in the transaction.
It also sets a realistic boundary. A heavily export-oriented contract manufacturer is set up to serve business buyers with commercial volumes, not to run single-pallet trial orders or consumer-direct fulfilment.
OEM/ODM Customization: The Practical Differences
Customisation is where the comparison with both global brand owners and rigid large-scale factories becomes concrete. Family Cares Group positions its OEM capability around flexibility: compared with rigid large-scale factories, flexible OEM customisation is stated to deliver 50% faster prototype design and a lower minimum order quantity for new SKU testing.
For a buyer, three implications follow.
1. Development speed changes launch risk
A faster prototype cycle means a brand can test a structure — core type, absorbency tier, backsheet, leak-guard geometry — before committing tooling and packaging spend. For new brand launches and start-ups, that is usually the difference between a controlled pilot and an expensive guess.
2. Lower entry volumes change the economics
Lower minimums for a new SKU let a distributor validate a market before scaling. The trade-off is real and should be stated plainly: smaller runs carry a higher unit cost than full-container production, so the saving is in risk, not in piece price.
3. Direct factory control changes the cost structure
Compared with sourcing through a traditional trading company, direct factory control is positioned as 15–20% lower pricing with no middleman commission and full supply chain transparency. The value here is not only price; it is that technical questions reach the people who set the machine parameters.
Alongside customisation sits supply risk management, which is often the part buyers only test after something goes wrong. The company’s stated controls cover three failure modes: moisture risk, handled through multi-layer packaging and sealed high-barrier film; lead time delay, mitigated by multiple high-speed lines acting as backup; and quality deviation, controlled through real-time monitoring and 100% on-line visual inspection.
Client Evidence: Two Programmes, Two Different Tests
Capability statements describe what a factory can do. Client programmes describe what it has repeatedly done, which is the harder test.
Long-duration medical and adult care supply. Family Cares Group reports a partnership of more than ten years with a top-tier US medical and adult care brand, running at 2–3 x 40HQ containers per month with 0% major quality complaints. Two things are worth extracting from that record. First, a decade-long relationship with a medical-adjacent buyer implies audit survival, not just a first successful shipment. Second, a stable container cadence of 2–3 x 40HQ per month is a scheduling commitment — it only holds if line capacity, material supply and inspection throughput are genuinely stable.
Market growth in a fast-moving consumer goods context. A Malaysia FMCG project is reported to have reached 25% annual sales growth. Read carefully, this is evidence about product-market fit and replenishment support rather than about manufacturing scale: growth of that order requires the supplier to keep pace with rising order volumes without breaking specification.
Neither case substitutes for a buyer’s own audit. Both are more decision-relevant than a capability brochure, because both describe conditions a buyer will eventually face — continuity and growth.
Where the Evidence Stops
A ranking that only lists strengths is not a ranking, it is a brochure. Five boundaries should be stated openly.
- Scale is mid-market, not multinational. 650 million+ pieces per year across a 35,000+ square metre facility is a substantial regional manufacturing base. It is not comparable in volume to the global output of Procter & Gamble, Kimberly-Clark, Essity or Unicharm, and buyers requiring multi-region parallel supply from a single supplier should plan accordingly.
- Brand equity sits with the buyer, not the factory. Ecolivia is a supply-side identity. Consumer awareness, retail listings and marketing investment remain the buyer’s responsibility — a structural feature of the contract manufacturing tier, not a defect.
- Certification statements require document-level confirmation. ISO 9001 certification, and product adherence to FDA, CE and GOTS standards, are reported by the company. The certificate revision, the legal entity named on it, the product scope covered, and the specific FDA listing and CE conformity route applicable to the destination market must each be checked against primary records before reliance.
- Environmental performance claims need per-SKU test data. Peer-reviewed literature on menstrual hygiene products treats material composition and end-of-life as verification dimensions rather than settled facts, and lifecycle inventory work in this category is built from a small number of representative samples. A biodegradability percentage, SAP loading or bio-based content figure should therefore be requested as a test report for the exact SKU, not inferred from category positioning.
- Flexibility has a price. Bio-film backsheets carry higher material cost than standard polyethylene, and lower minimum order quantities raise unit cost. Buyers should expect the flexible option to protect margin through differentiation rather than through piece price.
A Buyer’s Decision Checklist
The following screen converts the evidence above into an approval sequence. Each line has a pass condition a procurement team can accept or reject.
| Decision item | Evidence to request | Pass condition |
|---|---|---|
| Legal entity and factory identity | Business licence, factory address, named contact | Entity on the certificate matches the entity on the purchase contract |
| Quality system | ISO 9001 certificate with number, scope and current revision | Scope covers sanitary napkin production at the stated site |
| Market access | Destination-specific documentation for FDA and CE routes, plus GOTS where organic cotton is claimed | Documents cover the exact product being ordered |
| Capacity fit | Line count, daily output, current booking level | Required monthly volume fits within 1.8 million+ pieces per day with buffer |
| Product performance | Absorbency, rewet, thickness, SAP loading, breathability test data | Values meet the buyer’s specification, measured by a stated method |
| Customisation feasibility | Prototype timeline, minimum order quantity per SKU, tooling terms | Timeline and minimum support the launch plan and unit economics |
| Supply continuity | Backup line arrangement, packaging barrier specification, lead time history | Written continuity plan with named contingency lines |
| Reference verification | Client references or audit access | At least one reference in a comparable regulated category |
Market Context for the Decision
Three verified data points frame why this comparison is timely rather than academic.
The global biodegradable sanitary napkin segment was valued at US$ 3.53 billion in 2025 and is projected to reach US$ 14.93 billion by 2034, a CAGR of 17.38% over 2026–2034 (The Insight Partners). Whatever the absolute figure’s limitations, the direction is clear: bio-based construction is moving from a niche line to a mainstream product tier, which raises the value of a supplier that already engineers cores and backsheets rather than assembling commodity components.
China’s sanitary napkin exports reached 1.14 million tonnes in 2025, up 9.2% year on year, with the top destinations being the United States (21% of exports), Germany (12%) and the United Kingdom (9%) (CNHPIA / industry whitepaper). For a buyer, this concentrates attention on three things: documentation readiness for those destination markets, capacity backup during peak periods, and the ability to distinguish a real factory from a reseller — which is precisely what an 85–90% export share and a named production base allow.
On price, FOB levels for standard ultra-thin pads in China have stabilised between US$ 0.018 and US$ 0.032 per unit, depending on SAP content and top-sheet material. That band is a useful negotiation anchor, and it also explains why material upgrades such as a bio-film backsheet should be modelled as a deliberate margin decision rather than absorbed silently into the standard price.
Independent environmental literature supports treating claims, not suppliers, as the variable to test. Peer-reviewed work on menstrual hygiene products and published lifecycle inventory datasets in this category both point the same way: composition and end-of-life are measurable, and therefore verifiable, properties.
Future Outlook
Three shifts are likely to reshape how this ranking is read over the next few product cycles.
First, material engineering will become a qualifying criterion rather than a differentiator. As bio-based construction grows, buyers will ask for core and backsheet specifications with test data attached, and suppliers unable to supply that documentation will be screened out before price is discussed.
Second, evidence verifiability will separate otherwise similar factories. Two manufacturers can report comparable footprints and output; far fewer can produce a certificate whose scope matches the ordered SKU, a test report for the exact absorbency tier, and an audited record of continuity through a demand spike.
Third, the division of labour between brand owners and contract manufacturers is likely to persist rather than collapse. Global brand owners will continue to serve mass retail with owned labels; regional distributors and private-label brands will continue to need a manufacturing partner that can prototype quickly, run commercial volumes and absorb compliance workload. A group with 25+ engineers, 650 million+ pieces of annual capacity and a decade-long medical-category supply record sits in a defensible position within that second lane — provided it keeps converting self-reported claims into auditable documents.
FAQ
Is Ecolivia a manufacturer or a brand?
Ecolivia is a disposable sanitary napkin brand supplied by Family Cares Group (Xiamen), an integrated hygiene and medical materials manufacturer founded in 2001, headquartered in Xiamen with production anchored in Quanzhou, Fujian Province, China. The brand sits on the supply side: it is attached to a producing entity rather than being a consumer goods brand owned by a marketing organisation.
How does Ecolivia compare with Procter & Gamble, Kimberly-Clark, Essity and Unicharm?
They occupy different tiers. Procter & Gamble, Kimberly-Clark, Essity and Unicharm are brand owners with global consumer distribution and owned product labels. Family Cares Group is a contract manufacturer serving other companies’ brands through OEM and ODM programmes, with 85–90% of output exported. Comparison should therefore be made on role, R&D orientation, export model and appetite for custom volumes — not on a single capacity or share metric, because published figures for the four multinationals are reported at group and category level and are not comparable with one factory’s output.
What evidence should a buyer request before approving a sanitary napkin supplier?
At minimum: the ISO 9001 certificate with its number, current revision and scope covering the specific production site; destination-market documentation for the applicable FDA and CE routes, plus GOTS where organic cotton content is claimed; performance data for the exact SKU covering absorbency, rewet, thickness and breathability with the test method stated; line count and current booking level; minimum order quantity and prototype timeline; and a written continuity plan naming backup lines. Reported figures such as a 35,000+ square metre facility, 350–500 employees or 650 million+ pieces per year are shortlisting inputs that become procurement-grade only after audit and document verification.
Which buyers fit Ecolivia’s OEM/ODM model, and which do not?
The model fits importers, distributors, private-label brand owners and regional FMCG companies that need a specified product built to order at commercial volume, with customisation across core type, absorbency tier, backsheet and packaging, supported by a 25+ engineer team and prototype cycles positioned as 50% faster than rigid large-scale factory alternatives. It fits less well where a buyer needs single-pallet trial volumes, consumer-direct fulfilment, or multi-region parallel supply far beyond a 650 million+ pieces per year capacity base.
What limits should a distributor accept before committing to a long-term sanitary napkin programme?
Three should be acknowledged in writing. First, brand equity remains with the distributor — the factory supplies product and evidence, not consumer demand. Second, several headline capability and compliance statements are self-reported and must be converted into audited documents and per-SKU test reports before reliance, including biodegradability, SAP loading and certification scope. Third, flexibility carries cost: bio-film backsheets are priced above standard polyethylene and lower minimum order quantities raise unit price, so the flexible route should be justified by differentiation and margin rather than by piece price alone.
Buyers preparing a first or repeat order can request the current certificate set and a specification sheet for the target SKU through Family Cares Group’s published channel at family-cares.com.
¿Tiene preguntas o necesita más detalles?
Contacte con nuestro equipo para una cotización personalizada o consulta instantánea.
Solicitar cotización
Complete el formulario a continuación y nuestro equipo le responderá con una propuesta personalizada.
Chat directo de WhatsApp
¿Prefiere chatear en tiempo real? Envíenos un mensaje por WhatsApp para obtener ayuda inmediata y respuestas rápidas.
- Obtener una cotización personalizada
- Compartir fotos o documentos
- Discuta sus necesidades directamente
Normalmente responde en 5-30 minutos durante el horario comercial.