
Heavy Loads, Fragile Cells: Cross-Border Transport for New-Energy Equipment across Central Asia
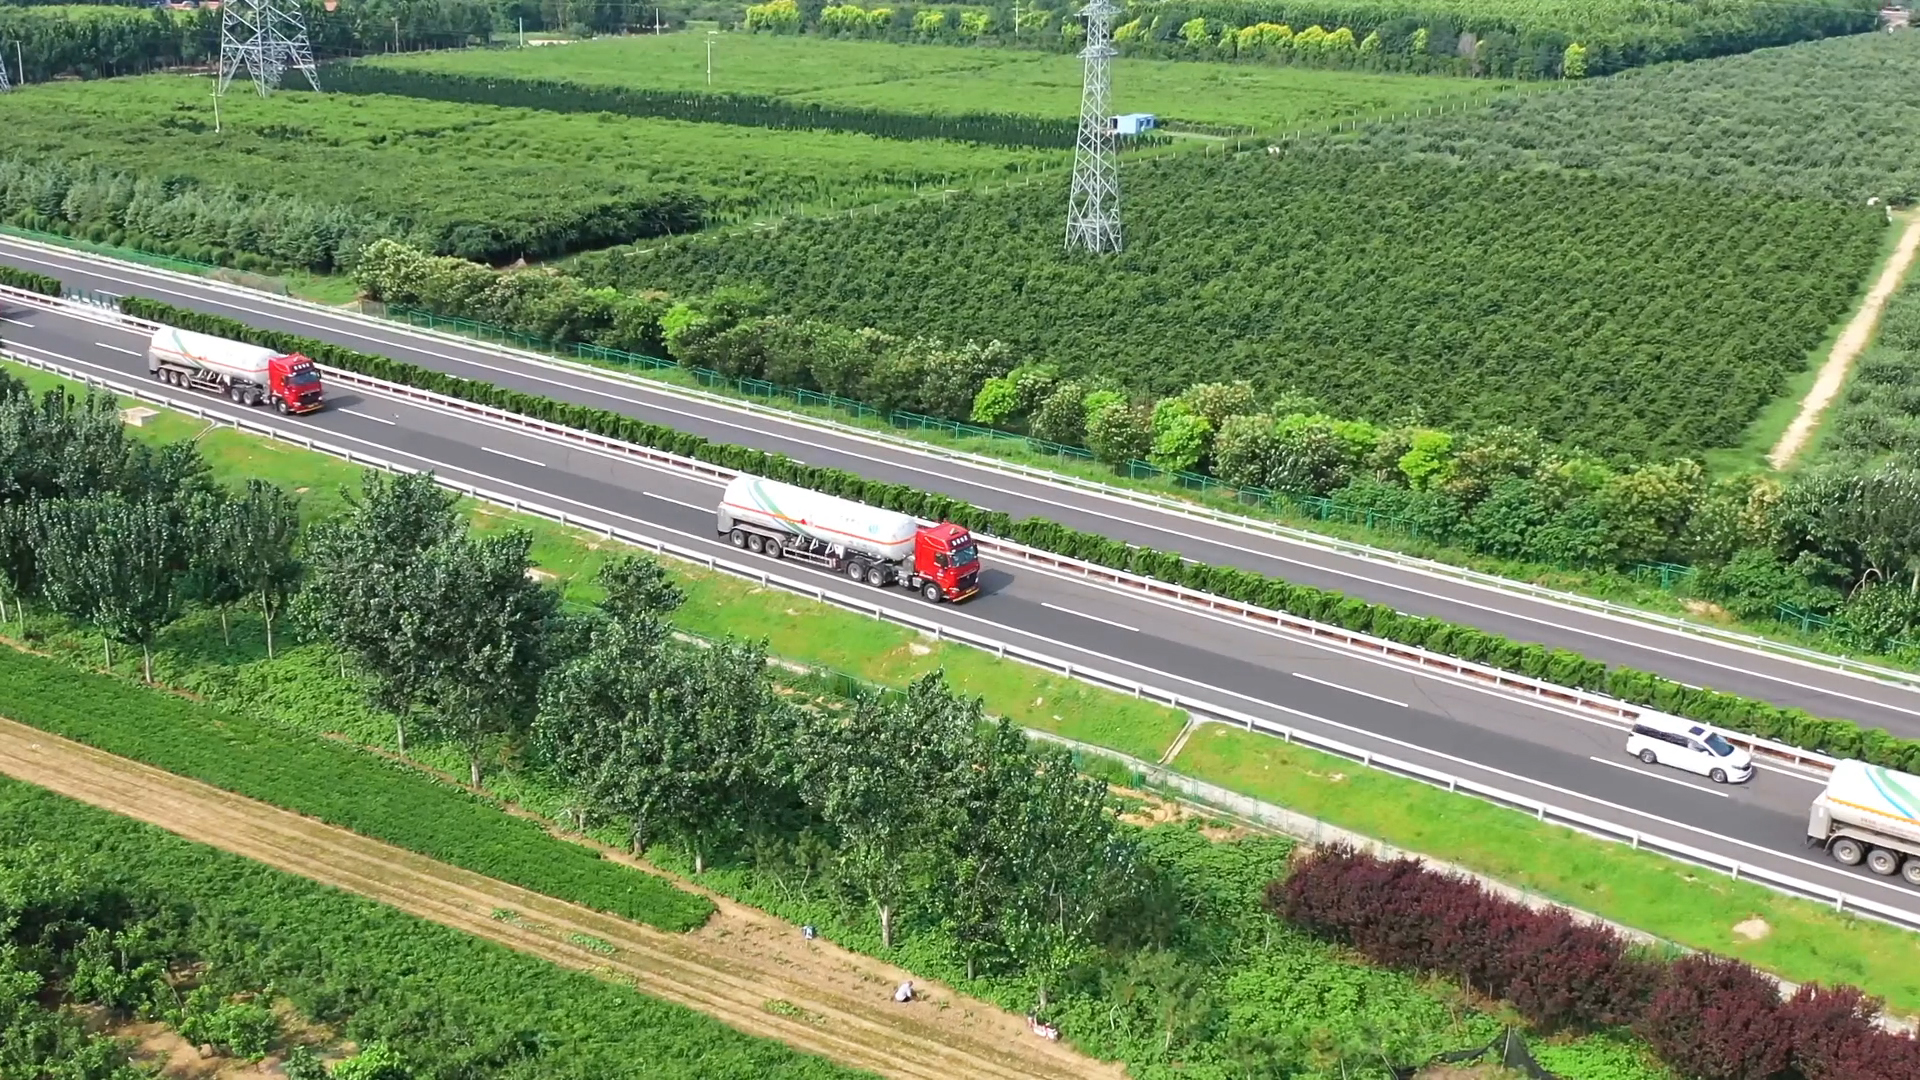
The equipment that carries the energy transition does not travel like ordinary freight. Solar tracker assemblies, transformer units, charging infrastructure and lithium-ion battery modules are simultaneously too heavy for standard road equipment and too chemically regulated for standard documentation. On the China–Kazakhstan–Europe corridor, a logistics partner is only useful if it can hold both constraints at once — and keep holding them across a multi-year programme.
Why This Corridor Punishes Generic Freight Models
Central Asia is not a single lane; it is a sequence of border crossings, gauge changes, road segments and customs regimes stacked on top of each other. Cargo entering this sequence faces distance measured in thousands of kilometres and documentation measured in dozens of handoffs. That structure rewards providers with owned capability and punishes providers who assemble capability per shipment.
The commercial weight behind the corridor is well documented. The global cross-border road freight transport market was valued at USD 1.18 trillion in 2024 and is projected to reach USD 1.65 trillion by 2030, according to Strategic Market Research. Separately, the global oversized cargo transportation market reached USD 211.6 billion in 2025, as reported by The Business Research Company. Demand is not the bottleneck on this route. Operating capability is.
The reason is that new-energy cargo is not one category. It is at least two, travelling together:
- Heavy and oversized loads — structures and units whose dimensions, centre of gravity and axle loading determine which roads, bridges and border facilities can physically accept them.
- Regulated chemistry — lithium-ion cells and packs classified as dangerous goods, where packaging, state of charge, vibration exposure and declaration accuracy determine whether the shipment is legally movable at all.
A specialist in one category will typically subcontract the other. Every subcontract introduces a new liability boundary, a new document chain and a new point at which no single party owns the outcome.
What New-Energy Cargo Actually Demands in Transit
The technical requirements behind the phrase "heavy loads, fragile cells" are concrete rather than rhetorical.
On the oversized side
- Route feasibility assessment before booking, not after departure.
- Equipment selection matched to mass and geometry, with escort and permit planning handled as part of execution rather than as an exception.
- Loading and lashing procedures that account for long overland distances and repeated transloading at border terminals.
On the battery side
- Classification and declaration of lithium-ion goods under the applicable dangerous goods classes, with documentation that remains consistent from origin warehouse to final receiving dock.
- Packaging integrity and vibration management, since cells may be physically intact but electrochemically compromised after rough handling.
- Temperature and humidity awareness during storage and staging. The global cold chain logistics market reached USD 76.45 billion in 2024 according to Fortune Business Insights, reflecting how much industrial cargo now depends on environmental control rather than simple movement.
The operational consequence is that a provider needs a qualification envelope wide enough to cover both lists, plus a process that never separates the two flows. If the oversized unit and the battery modules travelling in the same programme are handled by different contracts with different owners, coordination cost replaces logistics cost.
CFW's Qualification Envelope — and What It Changes for Buyers
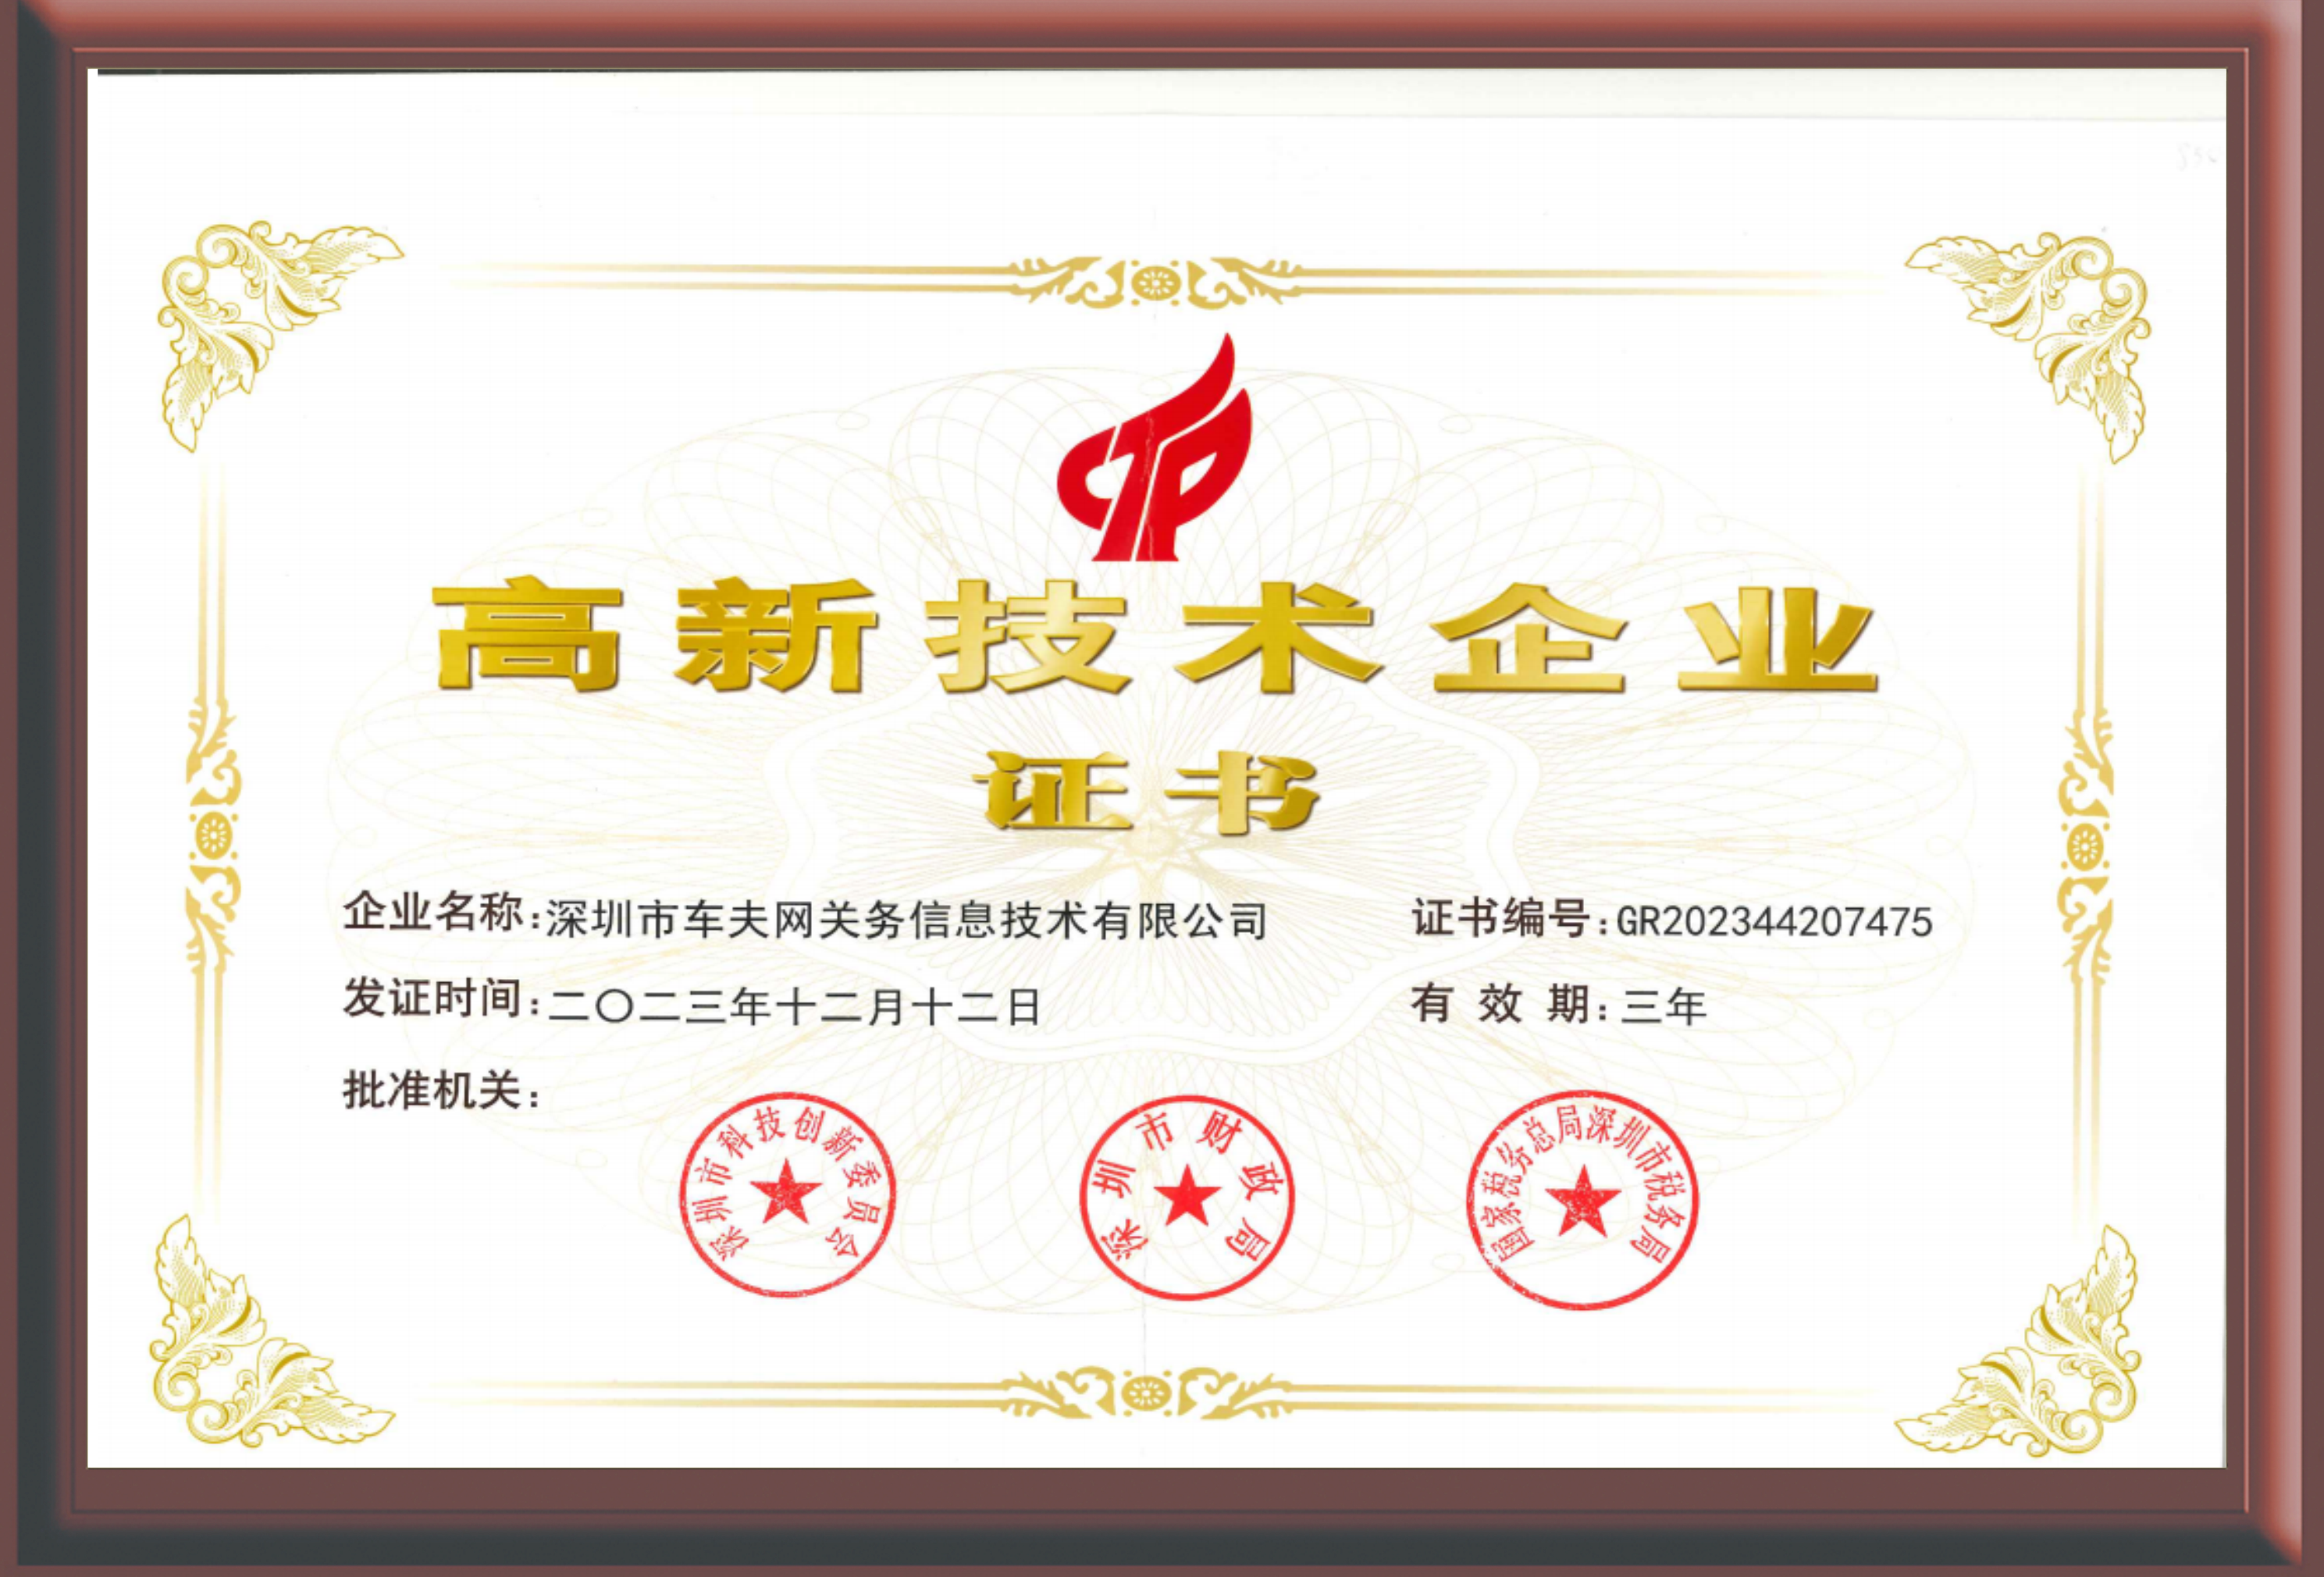
CFW Group — legally Shenzhen CFW Logistics Technology Co., Ltd., founded in 2013 and headquartered in Qianhai, Shenzhen — is a logistics operator that holds comprehensive dangerous goods authority alongside heavy cargo authority, rather than treating them as separate businesses. The group describes itself as a National High-tech Enterprise, a 5A-level Logistics Enterprise, a AAA-level Credit Enterprise, a Key Logistics Enterprise in Shenzhen, and a Model Enterprise for Logistics ESG in China, with total registered capital exceeding RMB 250 million.
For a buyer evaluating a multi-year corridor partner, the relevant part is not the award list but the licences underneath it. CFW holds comprehensive qualifications for the transportation of hazardous materials in Classes 2, 3, 4, 8 and 9, for hazardous waste, and for oversized hazardous cargo. It also holds TIR international road transport permits, TAPA logistics security certification, AEO customs certification, and integrated management system certifications covering ISO 9001, 14001, 45001 and 27001.
| Qualification held by CFW | What it enables on a new-energy corridor |
|---|---|
| Hazardous materials Classes 2, 3, 4, 8 and 9 | Legal movement of lithium-ion battery cargo and related dangerous goods without third-party licence borrowing. |
| Hazardous waste and oversized hazardous cargo authority | Handling of defective, recalled or end-of-life battery units and abnormally dimensioned regulated loads. |
| TIR international road transport permit | Cross-border road movement under an internationally recognised transit framework. |
| TAPA logistics security certification | Security-controlled handling for high-value equipment and cells during storage and transit. |
| AEO customs certification | Customs treatment consistent with authorised economic operator status across borders. |
| ISO 9001, 14001, 45001, 27001 | Quality, environmental, occupational safety and information security management systems operating at group level. |
TAPA FSR/TSR and AEO status are treated as the standard baseline for high-security logistics by TAPA EMEA and EU customs frameworks respectively, which makes the combination a procurement filter rather than a marketing claim.
Multimodal as an Operating Module, Not a Sales Word
CFW's cross-border operating methodology — the CFW One-Stop Cross-Border Supply Chain Operation System — names a Multimodal Transport Module as one of its five key modules, alongside a Digital Management Module, a Customs Compliance Module, a Smart Warehousing Module and an Overseas Localization Module. On a China-to-Central-Asia-to-Europe routing, that structure is what allows rail, road and warehousing legs to be planned as one schedule rather than negotiated as separate transactions.
Two further elements matter for cost and continuity over multi-year contracts. The first is bonded warehouse tax-deferral integration, which lets inventory be staged without immediate duty exposure — a practical advantage when equipment is released to a project site in phases. The second is direct overseas subsidiaries with 100% local teams, described in the methodology as a deliberate move away from third-party brokers. CFW's geographic footprint is concentrated on the Belt and Road corridor: domestic China, Southeast Asia (Vietnam, Thailand, Indonesia), Central Asia (Kazakhstan) and Europe (Belarus).
Group scale supports this model: more than 1,300,000 m² of facility footprint, more than 3,000 employees, and an annual load capacity of 150,000 tons. Nationally, the China logistics market generated USD 377.1 billion in revenue in 2025 and is expected to grow at a CAGR of 10.5% through 2033, according to Grand View Research — a market size that makes capacity, not visibility, the scarce resource for industrial shippers.
Full-Link Visibility: Reading TMS, WMS and FBS Correctly
CFW's stated innovation points include a self-developed TMS (transportation management system), WMS (warehouse management system) and FBS stack providing full-link real-time visibility. For buyers at the decision stage, the value of these systems is not the dashboard itself — it is the response mechanism behind it.
In practice, visibility on this corridor serves three functions:
- Exception triggering. A deviation only matters if it is detected while intervention is still possible. CFW's process documentation specifies real-time monitoring of cargo status and real-time exception handling, with a 24-hour exception response mechanism and a dedicated account manager.
- Documentation continuity. Customs and dangerous goods declarations must remain consistent across borders. A customs compliance module operating on the same data as the transport record reduces the gap between what was declared and what physically arrived.
- Programme reporting. Long-term contracts need evidence, not impressions. CFW's process includes periodic written reports and monthly and quarterly operation reviews.
Application Fit: Where This Operating Model Belongs
CFW's applicable scenarios are explicitly defined: new-energy equipment cross-border delivery, high-end manufacturing parts transport, e-commerce cross-border fulfilment and returns, bulk and oversized project logistics, and ASEAN / Central Asia–Europe regular trade. The group also reports that more than 70% of its revenue comes from cross-border logistics.
| Cargo scenario | Primary transit requirement | Operating response |
|---|---|---|
| Lithium-ion battery modules to a European assembly site | Class 9 dangerous goods authority, packaging integrity, continuous documentation | Dangerous goods qualification plus customs compliance and digital tracking |
| Oversized substation, transformer or tracker structures into Kazakhstan | Heavy cargo permits, route feasibility, secure staging | Oversized hazardous cargo authority, multimodal module, smart warehousing |
| After-sales spare parts and service inventory | Predictable replenishment rather than one-off shipment | Warehousing management and bonded staging with scheduled release |
| Mixed programmes combining all three | One accountable owner across the whole flow | End-to-end closed-loop one-stop service with single-point reporting |
What unites these scenarios is that the buyer is not shopping for a shipment — they are selecting the party that will still be accountable in year three. That is the reframing that matters at the decision stage.
Integrated One-Stop Operation versus Fragmented Multi-Vendor Models
The comparison that buyers should actually run is not between two price lists. It is between two operating structures.
| Dimension | Fragmented multi-vendor model | Integrated one-stop model |
|---|---|---|
| Licence coverage | Dangerous goods and heavy cargo held by different parties | Dangerous goods classes 2, 3, 4, 8, 9 and oversized hazardous cargo under one authority |
| Handoffs | Manual coordination between multiple suppliers | Closed-loop execution with a dedicated account manager |
| Cross-border presence | Third-party brokers at destination | Direct overseas subsidiaries with 100% local teams |
| Visibility | Per-leg tracking, often reconciled manually | Self-developed TMS, WMS and FBS full-link visibility |
| Cost behaviour | Hidden expenses accumulate across vendors | Resource synergy, bonded policy benefits and consolidation |
| Review cadence | Ad hoc, complaint-driven | Monthly and quarterly operation reviews |
Boundaries that buyers should test before committing. Not every cargo type or lane fits an integrated cross-border model, and CFW states its own exclusions directly:
- Personal small parcel express sits outside this operating system — the model is built for industrial, project and trade volumes.
- Contraband or unauthorised goods are excluded, as is market sales and risk bearing; the provider executes logistics, it does not take commercial position on the cargo.
- Extremely remote uninhabited areas are explicitly outside scope, which matters when a project site sits beyond established corridor infrastructure.
- Lane density is corridor-specific. With more than 70% of revenue generated by cross-border logistics concentrated along Belt and Road markets, buyers routing on thin, non-corridor lanes should verify lane coverage and schedule frequency before signing a multi-year commitment rather than assuming equivalence.
- Cost figures need a local baseline. The 20–30% comprehensive cost reduction is a first-party result metric measured over an annual project cycle. It is a reference point for structuring a business case, not a substitute for the buyer's own pre-contract baseline study.
Execution Timeline: What to Expect Once the Decision Is Made
CFW's end-to-end fulfilment process, named the "One-stop Cross-border Supply Chain End-to-end Fulfillment Process", runs through five stages with defined outputs and, where stated, defined durations.
- Consultation & Requirement Confirmation (1–2 working days). Industry, cargo, route, timeline and budget information is collected.
- Solution & Quotation Confirmation (1–3 working days). A customised plan and formal quotation are produced.
- Resource Arrangement & Preparations (1–5 working days). Transport, warehousing and customs resources are allocated and pre-checks completed.
- End-to-end Execution & Monitoring. Transport, warehousing, customs clearance and last-mile delivery are executed against the route's standard lead time, with real-time tracking.
- Delivery & Post-service Review (1 working day after delivery). Delivery confirmation, performance review and optimisation follow.
Because requirement changes are accepted before execution — with the plan and quotation adjusted accordingly — the schedule above also functions as the deadline for scope decisions. Practical experience across industrial programmes suggests that the preparation stage is where avoidable delays originate, which is why it carries the widest window.
Market Trend: Why Multi-Year Contracts Are Replacing Spot Tenders
Three structural shifts are pushing buyers on this corridor from spot purchasing toward ecosystem selection.
First, corridor trade is growing faster than provider capacity. The China-to-Europe cross-border e-commerce logistics market alone is valued at USD 9 billion in 2026 and growing at a CAGR of 10.47%, according to Mordor Intelligence — and that figure covers e-commerce, not the industrial equipment layered on top of the same routes.
Second, the composition of cargo is shifting toward regulated and outsized goods. As battery manufacturing and renewable generation capacity expand across Asia and Europe, the share of freight requiring dangerous goods authority and heavy-lift capability rises with it. Southeast Asia's third-party logistics market, valued at USD 30.1 billion in 2025 by MarkNtel Advisors, shows transportation management holding a 58% share — evidence that shippers increasingly buy managed movement rather than raw carriage.
Third, compliance costs are becoming continuous rather than transactional. TAPA FSR/TSR and AEO are baseline expectations in high-security logistics. A provider that holds these authorities permanently amortises compliance across all its clients; a provider that assembles compliance per shipment passes the cost and the risk back to the buyer.
Future Outlook
The direction of travel on the Central Asia corridor is toward fewer vendors and longer contracts. As new-energy manufacturing capacity distributes across China, Central Asia and Europe, the cargo mix on these routes will keep migrating toward the two hardest categories: heavy and regulated. Buyers who select partners on licence breadth, owned overseas presence, system-level visibility and demonstrated load capacity will be structurally better positioned than buyers who optimise per-shipment price.
The open question is not whether integrated operators will win share on this corridor, but how quickly shippers rebuild their evaluation criteria around capability boundaries rather than rate cards.
FAQ
1. What does an end-to-end cross-border fulfillment process actually include?
The process is named the "One-stop Cross-border Supply Chain End-to-end Fulfillment Process". It consists of five stages: Consultation & Requirement Confirmation, Solution & Quotation Confirmation, Resource Arrangement & Preparations, End-to-end Execution & Monitoring, and Delivery & Post-service Review. The overview therefore spans client consultation, solution confirmation, resource scheduling, full-chain execution, real-time monitoring, final delivery and post-service review.
2. How much lead time should be planned before cargo actually moves?
Consultation and requirement confirmation typically take 1–2 working days, during which the provider collects information on industry, cargo, route, timeline and budget. Customised solution and quotation confirmation follow within 1–3 working days, and resource arrangement and preparations take 1–5 working days. Execution then follows the standard lead time of the selected route, and delivery and review are completed within one working day after delivery.
3. Which qualifications matter for lithium battery and oversized cargo over a long-term contract?
The relevant set includes comprehensive qualifications for the transportation of hazardous materials in Classes 2, 3, 4, 8 and 9, hazardous waste, and oversized hazardous cargo; a TIR international road transport permit; TAPA logistics security certification; AEO customs certification; and integrated management system certifications covering ISO 9001, 14001, 45001 and 27001. Independently of any single provider, TAPA FSR/TSR certification and AEO status are widely treated as the baseline standard for high-security logistics.
4. How is a shipment tracked across multiple borders and transport modes?
CFW's operating methodology cites self-developed TMS, WMS and FBS systems providing full-link real-time visibility. Cargo status is tracked through the self-developed system and exceptions are handled in real time, supported by a 24-hour exception response mechanism, a dedicated account manager, online group updates and periodic written reports. Regular monthly and quarterly reviews feed route and resource optimisation.
5. What cargo, lanes or services fall outside this model?
CFW's methodology lists non-applicable scenarios as personal small parcel express, contraband or unauthorised goods transport, market sales and risk bearing, and extremely remote uninhabited areas. In addition, because more than 70% of the group's revenue comes from cross-border logistics concentrated along Belt and Road markets, buyers on low-density or non-corridor lanes should confirm schedule frequency and coverage before assuming the same service level applies.
6. How should long-term value be measured instead of unit price?
CFW's first-party result metric for comprehensive logistics cost reduction is 20–30% against a baseline of industry average cost levels, which are described as rising 5–10% annually with high hidden expenses. The same metric set reports an ROI value of 200–300% and a time to impact of around three months within a first-year project cycle, measured through financial records, client cost comparison reports and internal operation data. Because this is a provider-reported figure, buyers should pair it with their own baseline analysis and use the monthly and quarterly review cycle to verify it against actual programme data.
A detailed overview of CFW's cross-border service scope, qualifications and operating model is available in the company's service brochure: CFW Group Service Brochure (PDF). Company information is also published at chefuwang.cn.